Lagarde Told Markets France Must Fix Its Debt Crisis at Home, and the ECB Will Not Ride to the Rescue
ECB President Christine Lagarde said the answer to France's debt crisis lies at home in fiscal policy, playing down hopes of a Frankfurt backstop as French debt nears 120% of GDP and 10-year yields approach 5%.
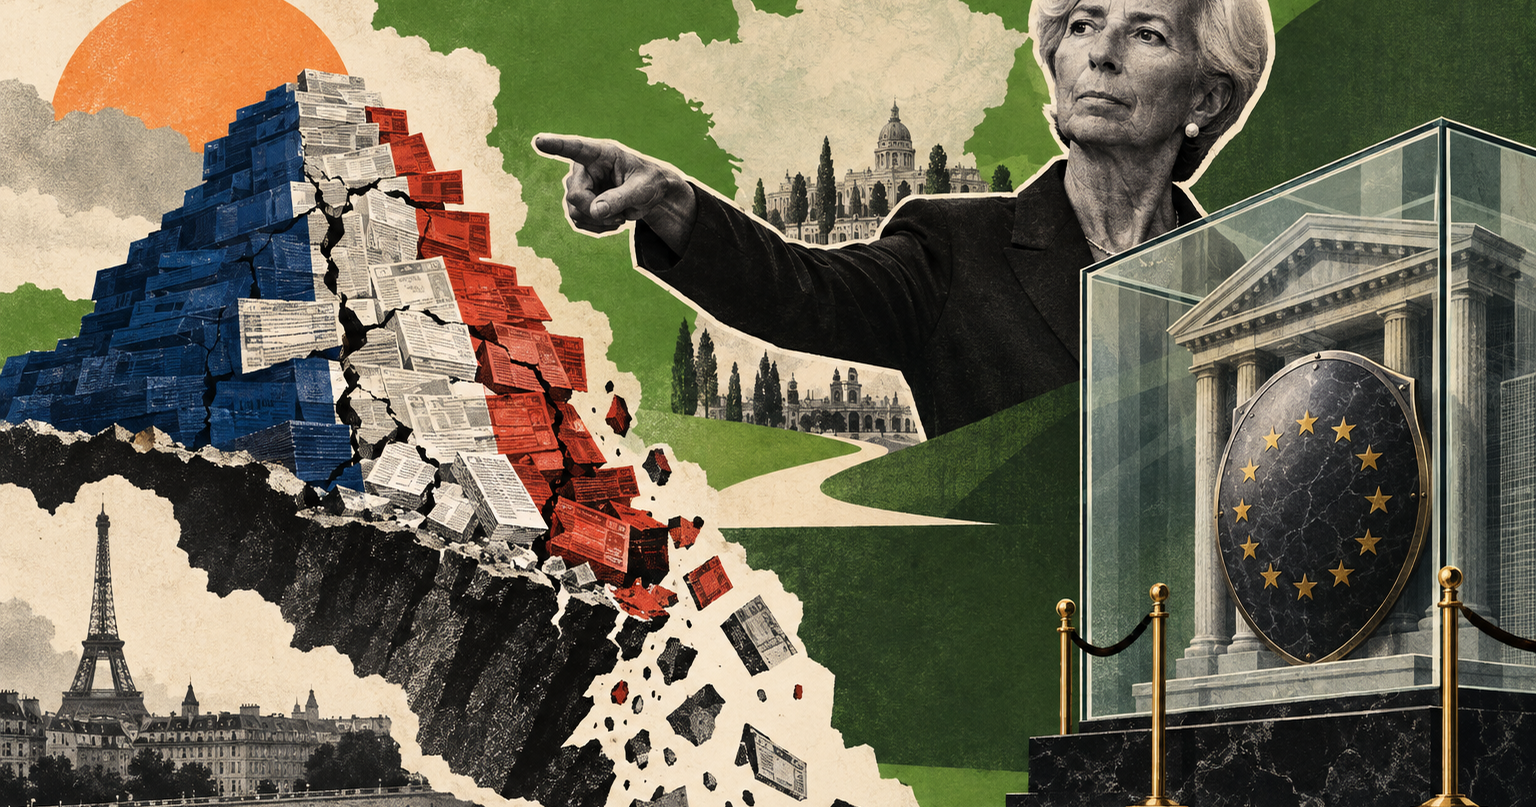
Investors hoping the European Central Bank would step in to calm France's debt crisis just got a clear answer from the top. Christine Lagarde said the fix has to come from Paris, not Frankfurt.
Asked at a CNN event in Bangkok whether the ECB planned to intervene in France's ballooning budget crisis, the ECB president pointed the problem straight back home.
"There are particular circumstances that lead to some countries being more affected, France being a case in point," Lagarde said. "For that one, the primary and first solution lies at home in France, and it has to do with fiscal policies."
Why markets were listening for a backstop
France is the European Union's second-largest economy, and its finances are in a precarious state. Public debt is nearly 120% of GDP. The benchmark 10-year bond yield has surged to nearly 5%, the highest in more than two decades, pushing up borrowing costs and slowing activity.
Those numbers have been moving fast. Spreads on French debt have already blown out to levels last seen in the 2012 euro crisis, and a central bank willing to buy bonds would be the obvious circuit breaker. Lagarde's words, which Reuters also reported, suggest traders should not count on it.
A crisis that snowballed in weeks
The pressure built quickly. Bond yields spiked while students staged unprecedented protests over overcrowded classrooms, teacher shortages and crumbling school buildings.
Paris has little room to answer those demands. High social welfare spending already eats up much of the budget, so any new money for schools competes directly with deficit cuts. Investors also worry that the political calendar will get in the way, with a presidential election coming next year making painful savings harder to push through.
That is the bind Lagarde left in place. The government has to persuade bond markets it can tighten spending while voters are in the streets asking for more of it.
Not just a French problem
Lagarde was careful not to cast France as the only weak link. Rising bond yields are not unique to the country, she noted. Yields in the US, Germany and Japan have also jumped recently, driven by rising government debt and a prolonged energy shock caused by the Iran war.
That global backdrop matters for France. When borrowing costs rise everywhere at once, investors get pickier about which governments they trust, and the countries with the thinnest fiscal cushions pay first. French fiscal fears have already rippled into currency markets, helping push the dollar to a 17-month high against the euro as a broader bond sell-off took hold.
Still, she singled France out as a case where local circumstances make things worse, and she placed the remedy squarely with French fiscal policy. For a market looking for a lender of last resort, that was the headline.
Some offers on this page may be paid placements or contain affiliate links.
Finpresso: daily AI & finance brief
Free daily newsletter, read in 5 minutes.
Subscribe free