Relay Review
Worth it when each cash bucket needs its own account number, because the savings rate is real and it does not touch the checking you pay from.
Relay is worth it in 2026 if you want many checking accounts and a savings yield, with no monthly fee on Starter. Grow is $30 a month and Scale is $90 a month ($120 list). Choose Mercury when a domestic wire should be free, Bluevine when checking itself should earn, and Novo when you will not pay for speed.
Savings APYs, accurate as of 17 September 2026, are 1.19% on Starter, 1.87% on Grow, and 3.21% on Scale. Checking does not earn, so the rate applies only to cash left in savings. A sole proprietorship stops at 10 checking accounts on Starter and Grow, below the allowance an LLC gets on those plans.
Prices below were verified on each vendor's pricing page in September 2026, and the wider cut is the business bank account roundup.
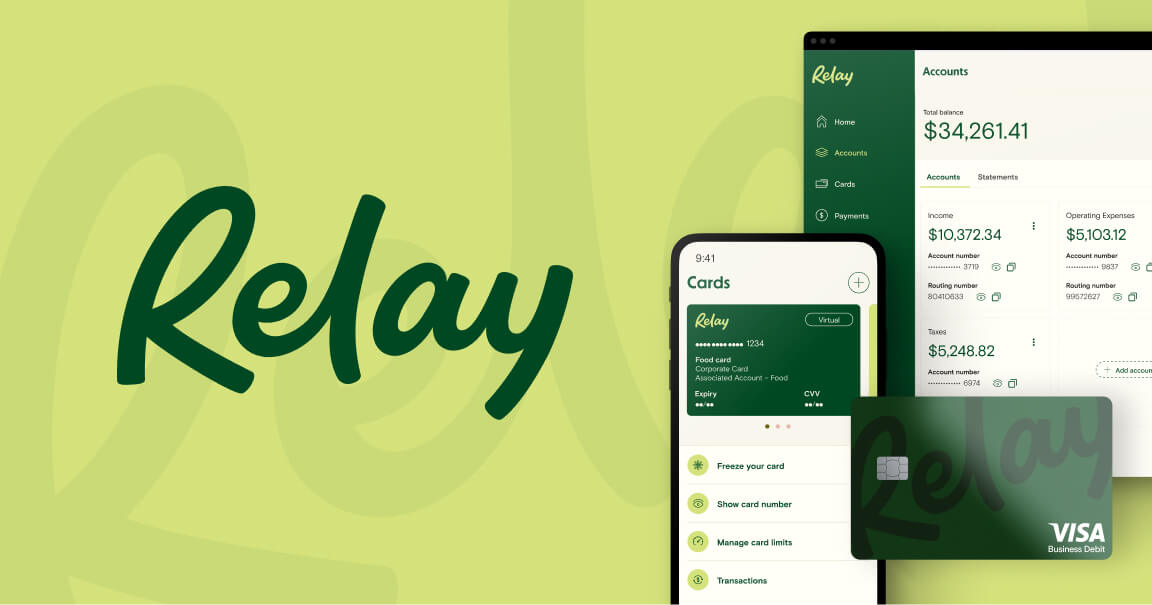
Relay is an envelope system with a routing number on each envelope. It is built for a bookkeeper who already splits tax, profit, and operating cash in a spreadsheet, and the free plan does that split.
The paid plans are a bet that a higher savings rate, or fewer per-payment fees, will beat the subscription.
That pays off only when idle cash sits in savings, or when the priced payments add up.
Toolradar data: the finance directory we maintain listed 1,040 tools in September 2026.
This page is the multi-account banking slice of that directory, not a ranking of every finance product in it.
Read Relay's directory page beside this review, then the Xero review if the feed into the ledger is the actual close problem.
Subscribe free when you want the next fee note in the Finpresso brief.
How we compared: Relay, Mercury, Bluevine, Novo, and Rho, priced in US dollars on 24 September 2026. Nobody paid for a slot, and we did not submit an application.
Plan math below multiplies the published savings APY by a balance that stays put for a year.
What is Relay?
Thread Bank, Member FDIC, holds the deposits and issues the Relay Visa debit card and the Relay Visa credit card, while the login is built by Relay Financial Technologies, Inc.
Relay's pricing page says it is a financial technology company, not an FDIC-insured bank, so the app and the charter are different companies.
The deposit agreement, last updated 1 September 2026, calls the checking account a non-interest-bearing demand deposit.
Yield sits on savings, so the checking you pay vendors from earns nothing on any plan.
Every plan includes two savings accounts, so a five-bucket Profit First layout can earn on two of those buckets and on none of the checking accounts.
Pass-through coverage is described as up to $3,000,000 when Thread Bank places deposits at program banks, at the standard $250,000 per bank, per ownership category, and only when the sweep conditions are met.
A balance above one bank's cap is insured only to the extent the sweep actually spreads it, so the headline figure is not automatic.
Relay's Profit First page calls the product the official banking platform for that method and says incoming money can split by percentage, by dollar amount, or by a built-in preset.
Those transfer rules are marked on every plan, including Starter, so you do not buy Grow to give a tax account its own number.
QuickBooks Online, Xero, Gusto, Plaid, and Yodlee are on the comparison table for every plan, and six months of Xero, for new Xero accounts only, is marked on Scale.
A rename inside Relay does not rename the matching account in Xero or QuickBooks. The Gusto review and the ledger still need a human to keep the names aligned after you add a bucket.
How Relay works
Relay boards US-registered businesses, and you must be at least 18 with a Social Security number, with owners of 25% or more listed. A sole proprietorship uses an SSN, while an LLC or corporation brings an EIN, and a non-US owner can apply if the business operates in the United States.
Personal accounts, escrow, trusts, and 401(k)s are out, and Thread Bank blocks some industries, among them cannabis and cryptocurrency.
Approval opens one checking account and one savings account, and an administrator adds more, nicknames them, and chooses who can see each one.
Starter and Grow allow 20 checking accounts, or 10 for a sole proprietorship, while Scale's cap is 50 checking accounts and savings stay at two.
A checking bucket cannot be flipped into savings later, so a tax reserve that should earn has to be opened as savings while a slot remains.
Standard ACH and incoming wires are not charged, while outgoing domestic wires, same-day ACH, local international wires, and SWIFT are priced by plan.
That grid is how a free sticker becomes a bill when you pay in a hurry.
International payments run through Community Federal Savings Bank, with Nium facilitating, and exchange is listed as little as 1%, so a dedicated FX desk belongs in the Wise review.
Cash comes in on a physical debit card, and an Allpoint+ ATM takes up to $1,000 a transaction with no Relay fee before 3:00 pm Eastern on a business day.
A Green Dot retailer can charge up to $4.95, and a virtual card cannot make that deposit, so a shop that takes cash should budget that retailer fee.
Employees get seven permission levels and advisors get five, with no per-seat fee, so headcount does not change the sticker.
Canceling a paid plan returns you to Starter and keeps the accounts, a mid-cycle upgrade is prorated, and Grow and Scale each offer a 14-day trial. Live phone agents are listed Monday through Friday, 11am to 4pm, and Scale promises faster phone and email, not a longer clock.
Relay key features
Relay pricing
Relay does not charge per person, so a two-person shop and a twenty-person shop pay the same sticker.
Headcount shows up as how many people can approve a bill, which is a Grow feature, and as how many same-day payments and wires the month actually sends.
The yield test uses only savings: multiply the 17 September 2026 APY by a balance that sits there all year, which is the flat-balance idea behind Relay's own calculator.
Checking is left out because the deposit agreement says it does not earn, so vendor cash should stay out of the yield math.
On $100,000 in savings, a year is $1,190 on Starter, $1,870 on Grow, and $3,210 on Scale. Grow's extra $680 against a year of subscription at $360 leaves $320.
That is the case where the higher rate pays for Grow and you still have the batch payments and recurring invoices.
On $40,000 the same method produces $476 on Starter and $748 on Grow. The gap is $272, short of that $360 year, so Grow at this balance is a workflow purchase.
You are buying approvals and a lower wire fee, not a profit on the interest.
A year of Scale at the discounted sticker is $1,080, and against Starter at $100,000 the extra yield is $2,020, so the discount still leaves the rate ahead.
At the published list price the same year costs $1,440, and the rate still leads until Relay ends the discount, which the pricing page labels limited-time.
Ten outgoing domestic wires come to $80 on Starter and $50 on Grow, before the subscription.
If wires are weekly, Mercury does not bill a domestic wire, and Plus is $29.90 a month.
Pro is $299, while a waiver through 31 December 2026 still leaves the FAQ opener at $35 a month.
Treasury waits on a large combined balance, and that sleeve is securities, not a deposit.
Bluevine can pay 1.3% APY on free checking, up to the cap in the table, in a month when you spend $500 on the debit card or take in $2,500.
That is yield on the account you pay from, which Relay checking does not offer.
Plus matches Grow's sticker at 1.75% on that cap, and Premier is $95 at 3.0% on the full balance.
Bluevine says those two fees can be waived, and a quiet Standard month is the month the checking rate does not apply.
Novo's fee schedule, revised 26 February 2026, prints 0% APY and no monthly service charge, so the free sticker holds until you pay for speed.
Express ACH is 1.5%, with a small floor and a cap, and an outgoing domestic wire is listed at up to $45.
Rho shows no subscription and no per-user fee, does not charge for ACH or wires, then lists optional SWIFT at $15 and conversion at 1%, so the free sticker is a domestic claim.
| Plan | Price | Best for |
|---|---|---|
| Relay Starter | No monthly fee | 1.19% savings APY and 20 checking accounts, 10 for a sole prop |
| Relay Grow | $30/mo | 1.87% savings APY, 14-day trial, batch payments and recurring invoices |
| Relay Scale | $90/mo, list $120 | 3.21% savings APY, 50 checking accounts, same-day ACH included |
| Relay same-day ACH | $1, then $0.50, then included | Starter, Grow, then Scale. Next-day ACH is not charged on any plan |
| Relay domestic wire out | $8 on Starter, then $5 | Grow and Scale match. Money arriving by wire is not charged |
| Relay local international | $5, then $3, then $1.50 | Local network by plan. SWIFT is the higher international line |
| Relay SWIFT | $25, then $22, then $20 | Starter, Grow, then Scale. Exchange is listed as little as 1% |
| Relay invoice ACH debit | 1%, 0.75%, or 0.5% | Capped at $10. Card payments on an invoice are 2.9% plus $0.30 |
| Mercury checking | No monthly fee | Domestic ACH and domestic wires are not billed |
| Mercury Plus | $29.90/mo | FAQ on the same page still cites $35, waived through 31 Dec 2026 |
| Mercury Pro | $299/mo | Named contact and NetSuite coding on top of Plus |
| Bluevine Standard | No monthly fee | 1.3% APY up to $250,000 if you spend $500 or take in $2,500 |
| Bluevine Plus | Billed monthly, or waived | 1.75% APY on that capped balance. The sticker matches Grow |
| Bluevine Premier | $95/mo, can be waived | 3.0% APY on the full checking balance |
| Novo checking | No monthly fee | 0% APY on the 26 Feb 2026 schedule. Domestic wire out up to $45 |
| Rho checking | No subscription | No per-user fee. Optional SWIFT $15. Conversion listed at 1% |
Relay pros and cons
What we like
- Starter includes transfer rules, two savings accounts at 1.19% APY, and up to 20 checking accounts (10 for a sole prop).
- Incoming ACH and incoming wires are not charged, and outgoing fees step down from Starter to Scale.
- QuickBooks, Xero, and Gusto are on every plan, with unlimited users and a separate advisor login.
What could be better
- Checking does not earn, and two savings accounts are the entire yield slot on every plan.
- Same-day ACH and outgoing domestic wires are billed on Starter and get cheaper only on a paid plan.
- Thread Bank holds the deposits and Relay is the software, and the deposit agreement lists live phone agents on a short weekday window.
Who Relay is for
Relay fits a US company whose books already think in buckets, and whose bookkeeper wants each bucket on the bank feed.
An LLC that parks idle cash in one of two savings slots, and pays vendors from checking, can stay on Starter.
Move to Grow when the APY gap covers a year of the plan, or when batch payments and recurring invoices are the reason even if the rate falls short.
Move to Scale past 20 checking accounts, or when same-day ACH should be included instead of billed per payment.
A sole proprietor who needs a dozen client accounts hits the cap of 10 on Starter and Grow and should not plan on the LLC limit.
Skip it when checking itself should earn, which is the Bluevine review, when domestic wires are weekly, which is the Mercury review, or when one account is enough, which is the Novo review.
Cards and payables as their own purchase are the corporate cards guide, the Ramp review, the Brex review, and the BILL review.
Best Relay alternatives
If Relay is not the right fit, these are the closest options.
| Tool | Best for | Starts at | |
|---|---|---|---|
| Relay | Bookkeepers who want an account number per cash bucket. | Starter free | Visit → |
| Mercury | Teams whose domestic wires are frequent enough that a per-wire fee adds up. | Free checking | Visit → |
| Bluevine | Operators who need the checking balance to earn, which Relay never does. | Standard free | Visit → |
| Novo | Firms that will skip yield to keep a single checking account off a monthly plan. | No monthly fee | Visit → |
| Rho | Teams that want domestic wires and bill pay without a Relay subscription. | No subscription and no per-user fee | Visit → |
The bottom line
Stay on Relay Starter when the job is account numbers and an automatic split, and the Starter savings rate is enough for cash you can leave untouched.
The subscription is justified when the extra yield on a large savings balance covers the year, or when batch payments, recurring invoices, or included same-day ACH are worth more than the rate.
Leave if checking itself should earn, because Bluevine pays on the deposit, or if a domestic wire should cost nothing, because Mercury does not bill that wire.
Leave if you will not use a second account number, because Novo keeps the monthly charge off the bill and pays no yield.
Leave if payables should not have a plan fee, which is Rho.
The wider comparison is the business bank account roundup, and you can subscribe free for the next pricing note.
Cite this: Finpresso, "Relay Review 2026: Pricing, Pros, Cons and Alternatives", September 2026.
This page is general information, not personalized financial advice, so confirm current rates, fees, and eligibility with Relay and Thread Bank before you apply.
Frequently asked questions
Get the Finpresso brief
Free daily newsletter, read in 5 minutes.
Subscribe free